Cash Runway: Formula and Worked Example for Loss-Making
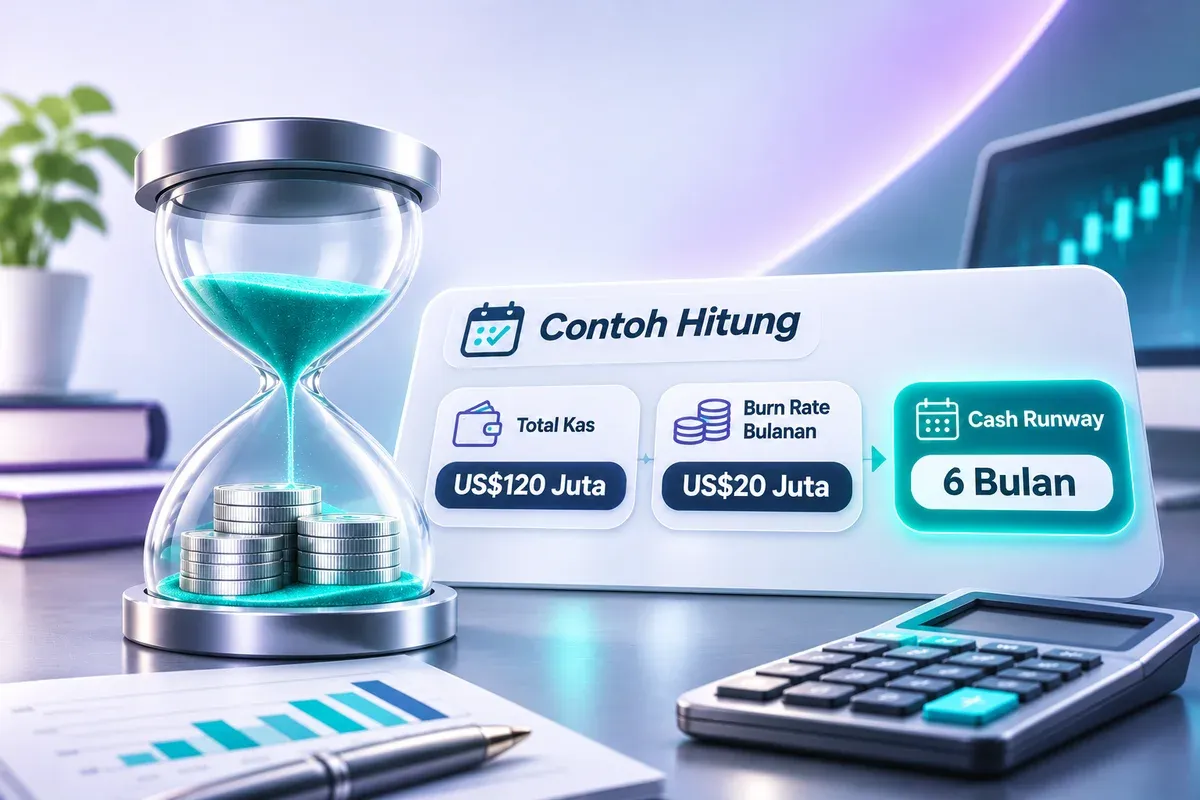
Cash runway is an estimate of how long a loss-making company can keep operating on the cash it has before it needs new funding. It is usually stated in quarters or months.
For Rivian and Lucid shareholders, it helps show whether the company has time to finish its production transition, or whether it may issue new shares that dilute existing owners. The calculation uses cash, quarterly burn rate, upcoming debt maturities, and funding plans.
Key Takeaways
- Core definition. Cash runway divides effective cash by the net quarterly burn rate to show how much operating time is left.
- Cash is not profit. Read the cash balance together with operating cash flow and capital spending, not the bank balance alone.
- Debt adds pressure. Debt due within 12 months reduces effective cash and can force funding earlier.
- Dilution is real. Raising money by issuing shares increases the share count and shrinks existing holders' stake.
- Run three scenarios. Test a base case, a tight case, and a funding case before judging a loss-making EV stock.
What Are Cash Runway and Burn Rate?
Cash runway answers a practical question: how long can the company last without extra funding? It is not a share price forecast, but a tool for reading how urgent funding is.
For capital-heavy companies such as EV makers, a short runway makes management more likely to accept expensive deals. The basics are also covered in our beginner's guide to stock investing.
Gross Burn and Net Burn
Gross burn is all the cash that leaves in a period. Net burn is cash out minus cash in from sales, so it is the figure that actually drains the balance.
Use net burn for runway. Include capital expenditure too, because EV makers often build plants and buy production equipment before revenue stabilizes.
Effective Cash, Not Gross Cash
Gross cash can mislead if part of the balance is restricted as collateral or held as minimum operating cash. Effective cash is cash and equivalents you can actually spend, after subtracting restricted cash and debt that is about to come due.
A small gap here can mean one extra quarter, or one quarter less.
Accounting Profit Is Not Enough
Accounting losses can differ from real cash outflow because of depreciation and other noncash costs. Look at the cash flow statement, not just the income statement.
If losses rise but burn improves, the risk may be lighter than it looks.
The Cash Runway Formula
The basic formula: runway (quarters) = effective cash divided by net burn per quarter. Multiply by three for an estimate in months.
1. Gather Cash and Equivalents
Take the figures from the latest balance sheet and separate restricted cash. Also check that short-term equivalents are truly liquid.
2. Calculate Net Burn per Quarter
Use operating cash flow and capital expenditure from the cash flow statement. Average at least three quarters so the trend is clear, rather than relying on one unusually good or bad period.
3. Separate Debt Due Soon
List principal and interest due in the next 12 months and subtract them from cash. If ignored, runway looks longer than the company's real capacity.
4. Divide Effective Cash by Burn
The result is the number of quarters left. This is a base case, not a certainty, because burn can change.
5. Test Tight and Funding Scenarios
Model higher burn, slower sales, and new money coming in. That gives you a range instead of a single number.
Worked Example with Illustrative Numbers
The numbers below are hypothetical and are not Rivian or Lucid data. Suppose an EV maker has US$6 billion in cash, net burn of US$1 billion per quarter, and US$0.8 billion of debt due within 12 months.
Gross runway is 6 quarters. After subtracting the debt, effective cash is US$5.2 billion, so runway is about 5.2 quarters, or roughly 15.6 months.
If burn rises 20 percent to US$1.2 billion per quarter, runway shrinks to about 4.3 quarters. A seemingly small rise in burn can cut the time considerably.
| Scenario | Effective cash | Burn per quarter | Runway | Note |
|---|---|---|---|---|
| Base | US$5.2 billion | US$1.0 billion | 5.2 quarters (about 15.6 months) | Enough time if execution is steady |
| Tight (burn up 20%) | US$5.2 billion | US$1.2 billion | 4.3 quarters (about 13 months) | Funding may be closer |
| Funding (US$2 billion new money) | US$7.2 billion | US$1.0 billion | 7.2 quarters (about 21.6 months) | More time, but dilution must be counted |
For Rivian and Lucid, replace the illustrative figures with cash, burn, and debt from each company's latest official filings. Do not use a single news headline as the basis for the calculation.
Debt Maturities and Effective Cash
Debt complicates runway because cash is not used only for operations. Principal and interest are obligations that must be met or refinanced.
If cash is short, the options are refinancing or selling new shares, and the second hurts existing holders. How to read financial statements in general is covered in US stock fundamental analysis.
Principal and Interest Schedule
Much debt is repaid in installments rather than all at the end. Build a quarter-by-quarter schedule to find the heaviest period, since a spike in one quarter can trigger a sudden funding need.
Undrawn Credit Facilities
A credit facility helps only if its conditions are met and the lender is still willing to fund. Do not count the whole facility as cash without checking covenants and drawdown conditions.
Covenants and Market Access
Debt often carries minimum financial ratios or spending limits. A breach can accelerate repayment or shut off new financing, so check the notes to the financial statements.
How Much Runway Is Considered Safe?
There is no official standard. As a commonly used rule of thumb, runway above 18 months gives room to breathe, 12 to 18 months gives limited room, and below 12 months raises the urgency of funding.
These thresholds are only a guide. A company with strong access to capital can be comfortable with a shorter runway, while one with heavy debt can be under pressure even when runway looks long.
When a Company Needs to Raise Funds
Companies usually look for funding before cash runs out because negotiations take time. The closer runway gets to its end, the weaker management's bargaining position.
The market watches the size of the raise, the share price at the time, and how the money will be used. To judge whether that share price is fair, see how to calculate a stock's fair value.
Market Window and Share Price
Funding costs more when the share price is depressed or capital markets are quiet. Management can wait, but waiting adds cash risk.
Debt versus Equity
Debt does not dilute shares directly, but it adds interest costs and covenants. Equity brings cash without interest, but increases the share count.
Commitments from Large Shareholders
Backing from a large investor can reduce the risk of a failed raise. A verbal commitment is not a binding agreement, so check official announcements and terms.
Dilution and How to Read It
Dilution happens when a company issues new shares or instruments that can become shares. Each extra share splits ownership and future profit across more holders. The mechanics of shares are explained in how stocks work.
A hypothetical example: a company has 1 billion shares outstanding and issues 200 million new ones. Existing holders' stake falls from 100 percent to about 83.3 percent.
New Shares Outstanding
Dilution is not always bad if the money funds growth that eventually produces cash. Without a path to profitability, dilution can repeat.
Earnings per Share
Earnings per share is profit divided by shares outstanding. More shares mean smaller earnings per share when profit finally turns positive.
Options, Convertibles, and Warrants
Dilution does not come only from new share issues. Employee options, convertible bonds, and warrants can also add shares later, so read the notes to the financial statements.
Variable-Price Conversion Financing
Emergency funding with a conversion price that follows the market can be very costly when the share price falls. The lower the conversion price, the more shares are issued.
How to Extend Cash Runway
Runway can be extended by cutting burn or adding cash. For EV makers, measures management commonly discusses include:
- Cutting operating costs. Reducing spending that does not directly support production and sales.
- Delaying capital spending. Pushing back plant or expansion projects that are not urgent.
- Improving margins. Raising selling prices or lowering production costs, including battery costs.
- Selling assets or finding partners. Turning noncore assets into cash or sharing investment costs.
- Raising funds. Through debt or new shares, with interest or dilution as the trade-off.
Common Mistakes
- Using the income statement instead of cash flow. An accounting loss is not the same as cash leaving.
- Relying on a single quarter. One quarter can be unusually good or bad.
- Ignoring capital expenditure. Runway looks longer than reality.
- Counting restricted cash as free cash. Money that cannot be spent gets included.
- Forgetting debt and interest payments. Obligations coming due are left out.
Checklist for Rivian, Lucid, and Other EV Stocks
Use this checklist so your analysis does not stop at the growth story. Focus on cash, burn, debt, and evidence that operations are improving.
- Read the latest filings. Start with cash, equivalents, and restricted cash on the balance sheet, then match them to the cash flow statement.
- Compare burn across three quarters. Falling burn alongside rising production is a better sign.
- Check debt due in 12 months. See whether cash covers it without new funding.
- Model a funding scenario. Assume an amount raised, a share price, and new shares issued, then see the effect on ownership.
- Track production and margins. Runway should improve through operations, not only through funding.
Conclusion
Cash runway helps answer how long a loss-making company can last on the cash it has. For Rivian and Lucid stock, read cash, burn rate, debt maturities, and potential funding together.
If runway is short and access to capital is limited, dilution risk rises and an investment thesis needs more caution. Always use the latest official filings, not media summaries.
FAQ
What is cash runway for a loss-making company's stock?
Cash runway is the estimated operating time left, calculated as effective cash divided by net burn per quarter. It shows how soon the company needs new funding or deeper cost cuts.
How do I calculate cash runway?
Divide effective cash by net burn per quarter. For example, US$100 million of effective cash and US$25 million of burn per quarter gives about 4 quarters, or 12 months.
What is the difference between gross burn and net burn?
Gross burn is all the cash that goes out. Net burn is cash out minus cash in from sales, and it is the figure used to calculate runway.
How does debt coming due affect cash runway?
Debt coming due reduces effective cash because it must be repaid or refinanced. If US$20 million is due within 12 months, US$100 million of cash drops to US$80 million before runway is calculated.
How much cash runway is considered safe?
There is no official standard. A common rule of thumb: above 18 months is relatively comfortable, 12 to 18 months is limited, and below 12 months is urgent.
When does a company need to raise funds, and what is the dilution impact?
Companies usually start looking for money when runway nears 12 to 18 months. Raising equity increases shares outstanding, so earnings per share and existing holders' ownership percentage can fall.
Can Rivian's and Lucid's cash runway be determined from a single report?
No, because cash, burn, debt, and capital spending change every quarter. Use the latest official filings and compare several periods before drawing a conclusion.
Is cash runway only relevant for startups?
No. Any company with negative cash flow, including large manufacturers investing in plants, should track runway.
Learn About EV and US Stocks on Mobee
Once you can read runway, you can start studying US stocks with amounts that suit you. Mobee is operated by PT CTXG Indonesia Berkarya, which is licensed and supervised by OJK.
Mobee offers selected US stock tokens and ETFs, and the list can change, so check the Mobee Stocks page or the app. A stock token is not the share itself, and the difference is explained in US stock tokens vs regular stocks.
New to this? Read how to trade stocks on your phone, then install the Mobee App.
Disclaimer
This article is for education only and is not investment advice or a recommendation to buy or sell any asset. The figures in the examples are hypothetical and are not Rivian or Lucid data.
Stocks and digital assets are high risk, and you may get back less than you invest. Do your own research (DYOR) and use only funds you can afford to put at risk.
 Direct market access from the app
Start exploring digital assets with Mobee
Track the market, learn about digital assets, and start trading more conveniently with the Mobee App.
Mobee is licensed and supervised by the OJK. Not a solicitation to buy or sell any asset.