Investing for Beginners: The Most Practical Order of Steps
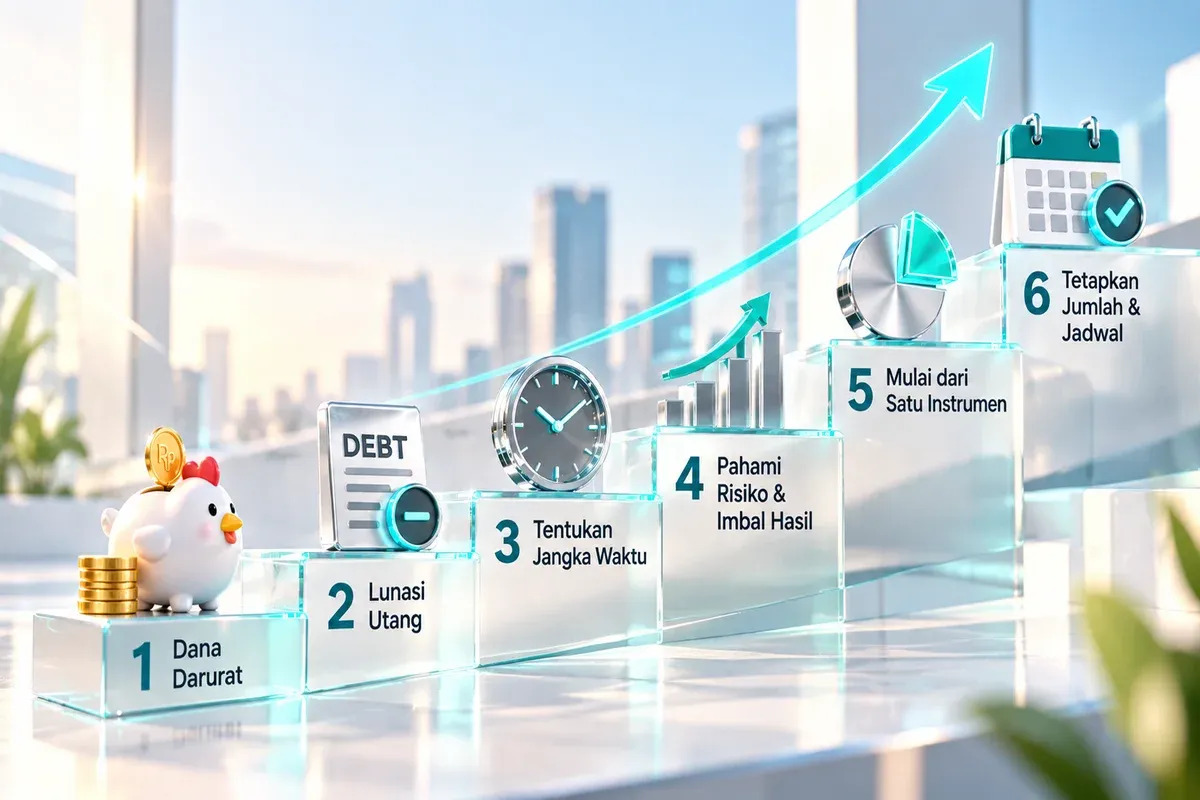
What determines a beginner's investment outcome is often what happens before choosing an asset: whether you have an emergency fund, whether you still carry high-interest debt, and how long you can leave the money untouched.
This article lays out the steps in a more practical order.
Key Takeaways
- Building an emergency fund and paying off high-interest debt should come before investing.
- Your time horizon should determine the investment instrument, not the other way around. Money you need next year should not be placed in an asset that could fall 30%.
- Higher returns always come with higher risk. Anyone promising high returns with little or no risk should be treated with caution.
- High-risk assets such as crypto are not necessarily the best place to start, but they may become a small part of a portfolio once the foundations are in place.
- Consistency in how much and how often you invest is generally more practical than trying to predict the perfect time to enter the market.
Step 1: Build an Emergency Fund First
This is one of the most commonly skipped steps because it feels boring, yet it is also one of the main reasons beginner investment plans fall apart.
Why This Comes Before Investing
Without an emergency fund, every unexpected expense can force you to sell your investments.
The problem is that emergencies often happen at the same time as difficult market conditions, such as during widespread layoffs.
You may be forced to sell when prices are low, turning what could have been a temporary loss into a permanent one.
How Much Should You Have?
A commonly used guideline is three to six months of monthly expenses for salaried workers and six to twelve months for freelancers or people with irregular income.
Keep the money somewhere liquid and relatively stable, such as a savings account or short-term time deposit.
An emergency fund is not an investment and does not need to generate high returns. Its purpose is to prevent you from having to touch your investments when unexpected expenses arise.
Step 2: Pay Off High-Interest Debt
If you have credit card debt or online loans charging interest of tens of percent per year, paying them off may be one of the most effective financial decisions available to you.
The reasoning is simple.
Paying off debt with a 24% annual interest rate effectively saves you 24% per year, with certainty and without market risk.
No investment can reliably promise the same return without risk. Claims that suggest otherwise should be treated with caution.
For lower-interest debt such as a mortgage, the calculation is different, and paying it off early is not always the best option.
Step 3: Decide Your Time Horizon Before Choosing an Investment
Start by Asking When You Will Need the Money
The better question is not "What is the best investment?" but "When will I need this money?"
| Time Horizon | More Reasonable Options | What to Be Careful With |
|---|---|---|
| Less than 1 year | Time deposits, money market instruments | Stocks, crypto, highly volatile assets |
| 1 to 3 years | Bonds, money market instruments, a small allocation to stocks | Large allocations to volatile assets |
| 3 to 10 years | Stocks, equity mutual funds, gold | Putting everything into one asset |
| More than 10 years | Stocks, with the possibility of a small allocation to higher-risk assets | Constantly switching investments every year |
A Practical Rule
Money with a fixed deadline should not be placed in assets that can fall sharply in the short term.
That does not mean the asset is bad. The problem is that the deadline may force you to sell at a time you did not choose.
Step 4: Understand the Relationship Between Risk and Return
One principle is worth accepting from the beginning: higher potential returns generally come with higher risk.
There is no long-lasting exception.
There Is No High Return Without Risk
Time deposits offer relatively modest returns because the risk of losing your principal is generally low.
Stocks may offer higher long-term growth potential because their value can fall significantly in the short term.
Crypto can move even more dramatically in either direction.
A Simple Filter for Investment Offers
This leads to a useful filter when evaluating investment opportunities.
If someone promises high returns with low or no risk, you are probably not looking at a rare opportunity but at something that deserves serious scrutiny.
A fixed monthly return from an asset whose market price freely fluctuates is a contradiction that should raise questions.
Step 5: Start with One Investment, Not Five
Beginners are often tempted to buy small amounts of many different assets at once because it feels like diversification.
What may actually happen is that you pay multiple transaction costs for a portfolio containing assets you do not yet understand.
It can be more practical to start with one investment you understand, using an amount that does not affect your peace of mind, and observe it for several months.
What you learn during that period is not only about the market but also about yourself: how you react when the value falls 15%, and whether you can really leave the investment untouched.
Diversification still matters, but it can be built gradually as your understanding grows rather than purchased all at once on the first day.
Step 6: Set an Amount and Schedule, Then Stick to It
Trying to identify the perfect entry point is difficult even for professional fund managers.
A more practical alternative is to invest a fixed amount on a fixed schedule instead of debating the price every time.
This approach does not guarantee that you will buy at the best possible price.
What it does is remove one decision that investors often struggle with: deciding exactly when to invest.
Learn more in what is dollar cost averaging.
Where Does Crypto Fit into This Order?
When Crypto May Make Sense
Crypto does not necessarily need to be the first place you start.
It may make more sense after you have built an emergency fund, paid off high-interest debt, and gained some experience watching the value of your investments fall without panicking.
Once those foundations are in place, a small allocation may be considered for long-term goals.
The size can be guided by one question: how much could you lose completely without changing your overall financial plan?
Five percent of a portfolio is sometimes used as a reference point, but there is no requirement to use that number.
Where to Start
If you reach that stage, start with what is crypto to understand the asset class, followed by how to buy crypto for the technical steps.
Before buying anything, also read about common risk management mistakes made by beginners.
For a more stable asset category, gold is often considered an accessible starting point.
Our comparison of physical and digital gold explains which form may be more suitable for different needs.
Frequently Asked Questions
How much money do I need to start investing?
Many investment products can be started with tens of thousands of rupiah. The starting amount matters less than consistently adding to your investments over time.
Is it better to save or invest?
They serve different purposes. Savings are generally used for short-term needs and emergency funds, while investments are intended for longer-term goals where your money may need to grow faster than inflation.
Do I need a financial advisor?
A financial advisor can be useful if your situation is more complex, such as managing an inheritance, a business, or several types of debt. For basic financial planning, understanding the core principles yourself may often be sufficient.
What if the value of my investment falls?
Price declines are normal and will happen repeatedly. What matters is ensuring that the money is not needed in the near future, so you are not forced to sell while the asset is down.
Is it safe to put everything into one investment?
It is generally not recommended, but spreading money across too many investments too quickly is not necessarily the solution either. Diversification can be added gradually as your understanding grows.
This article is provided for educational purposes only and does not constitute investment or financial advice. Every investment instrument carries risk. Conduct your own research and consider your personal financial situation before making any decision.
 Direct market access from the app
Start exploring digital assets with Mobee
Track the market, learn about digital assets, and start trading more conveniently with the Mobee App.
Mobee is licensed and supervised by the OJK. Not a solicitation to buy or sell any asset.